Bologna's Final 8: The Draw Took Three Lines, the Contract Is Still Unsigned
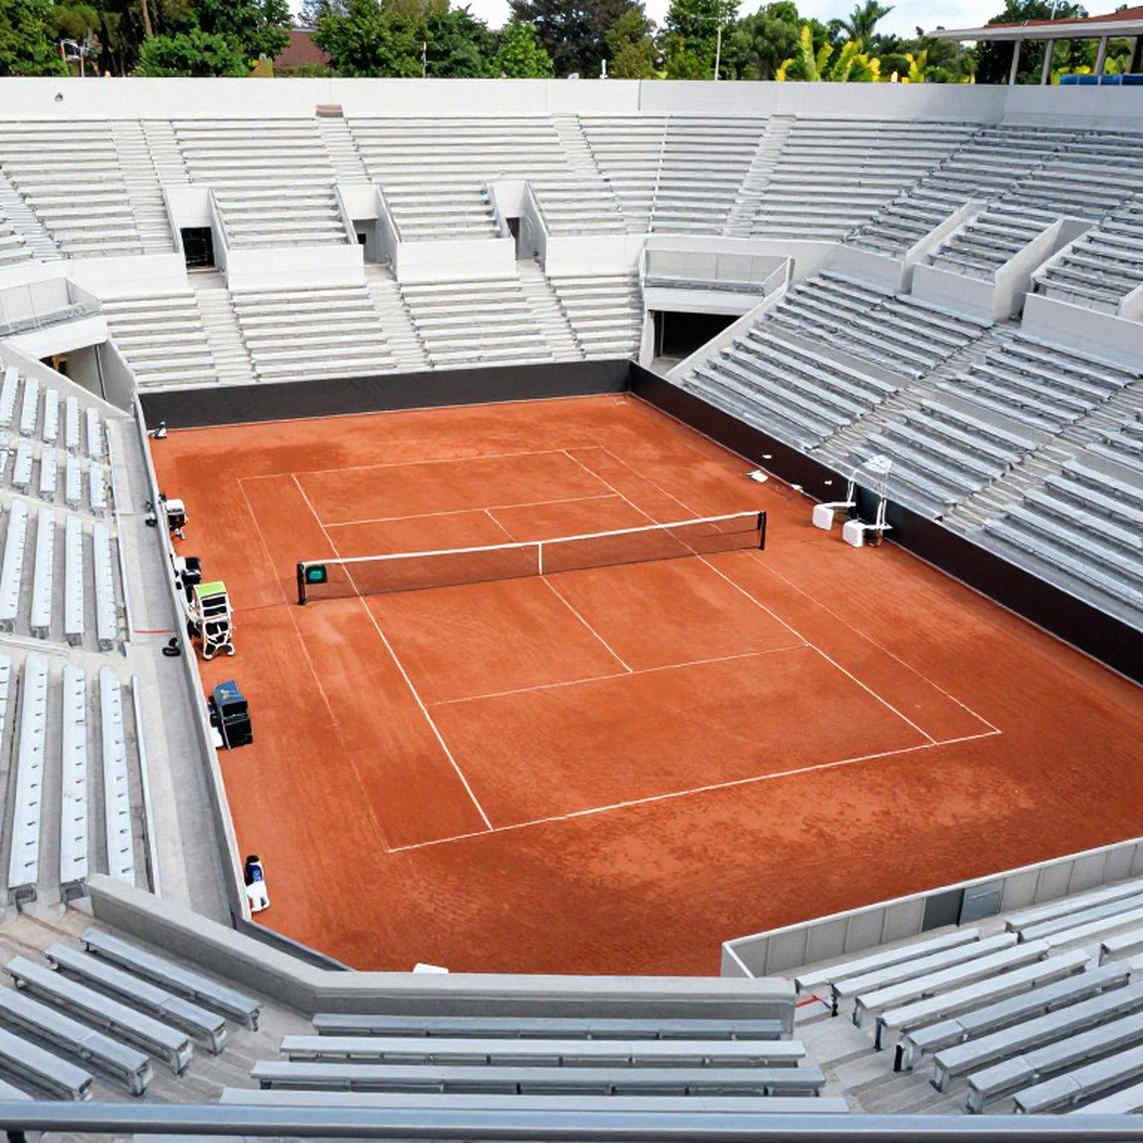
**মূল উত্তর:** ডেভিস কাপ ফাইনাল এইট ২৪ থেকে ২৯ নভেম্বর বোলোনিয়ার সুপারTennis এরিনায় ইনডোর হার্ডকোর্টে হবে। ড্র অনুযায়ী ইতালি–দক্ষিণ কোরিয়া, চেক প্রজাতন্ত্র–কানাডা, ব্রিটেন–জার্মানি ও অস্ট্রিয়া–স্পেন মুখোমুখি হবে; ইতালি টানা চতুর্থ শিরোপার লক্ষ্যে খেলছে। **মূল তথ্য:** - ইতালি টানা তিনবার চ্যাম্পিয়ন, চতুর্থ শিরোপার লক্ষ্যে; reigning champion হিসেবে স্বয়ংক্রিয় প্রবেশ পেয়েছে। - কোয়ালিফায়ারে ১৪টি দেশ খেলেছে, সেখান থেকে ৭টি ফাইনাল এইটে উত্তীর্ণ হয়েছে। - যুক্তরাষ্ট্র ৩২ বারের চ্যাম্পিয়ন হয়েও কোয়ালিফায়ারে চেক প্রজাতন্ত্রের কাছে হেরে ফাইনাল এইটে নেই। - দক্ষিণ কোরিয়া প্রথমবার ফাইনাল এইটে; আট দলের সাতটি ইউরোপীয়, কানাডা একমাত্র অ-ইউরোপীয়। - ডেভিস কাপ এটিপি র্যাঙ্কিং পয়েন্ট ব্যবস্থার বাইরে; অংশগ্রহণ জাতীয় নির্বাচনের ভিত্তিতে। - ফাইনাল এইটের উইন্ডো এটিপি ফাইনালসের পরপর, ২৪ থেকে ২৯ নভেম্বর। **সূত্র উল্লেখ:** রিউটার্স ওয়্যার রিপোর্ট (ডেভিস কাপ ফাইনাল এইট ড্র)। প্রকাশকাল অস্পষ্ট — বডি ডেটলাইনে বছর উল্লেখ নেই, শুধু একটি ছবির ক্যাপশনে '১৯ সেপ্টেম্বর, ২০২৬' আছে; এই তথ্য স্বাধীনভাবে যাচাই করা হয়নি, cricsultan.com ডাটাবেসের সঙ্গে ক্রস-চেক করা হয়নি। **সম্পর্কিত প্রশ্নোত্তর:** - প্রশ্ন: ডেভিস কাপ ফাইনাল এইট কোথায় ও কখন? উত্তর: বোলোনিয়ার সুপারTennis এরিনায়, ইনডোর হার্ডকোর্টে, ২৪ থেকে ২৯ নভেম্বর। - প্রশ্ন: আলেকজান্ডার জেভেরেভ কি সদ্য ইউএস ওপেন চ্যাম্পিয়ন? উত্তর: রিপোর্টে এভাবে দাবি করা হয়েছে, কিন্তু এখানে কোনো প্রাথমিক সূত্র দিয়ে তা যাচাই করা হয়নি, তাই এটিকে যাচাই-বাকি দাবি হিসেবে ধরা উচিত। - প্রশ্ন: ইতালির চতুর্থ টানা শিরোপার সম্ভাবনা কতটা? উত্তর: Format অনুযায়ী দুই সিঙ্গলস ও এক ডাবলসের ছোট ম্যাচসংখ্যা স্কোয়াড-গভীরতাকে বড় সুবিধা দেয়, তাই ইতালি কাগজে এগিয়ে; তবে এই সূত্রে কোনো খেলোয়াড়-Statistics না থাকায় এটি সতর্ক অনুমান।
November 24 to 29, SuperTennis Arena, Bologna, indoor hardcourt. The Davis Cup Final 8 draw took three lines: Italy v South Korea, Czech Republic v Canada, Britain v Germany, Austria v Spain. In wire-service language that is a fixture announcement. In my ledger it is a cost sheet with the biggest line still blank, because the contract that will price Bologna's seats, corporate boxes and screens in late November is not the draw. It is the roster.
Two things stopped my pen in the report. The dateline carries no year, and the only complete date in the text appears in a photo caption: September 19, 2026. Alexander Zverev is then described as a newly crowned US Open champion. Both are assertions, not evidence, so in this piece they stay as quotations, not foundations. Years of reading sponsor decks, media decks and audit sheets taught me that one wrong number can destroy an entire sponsor category. Remote auditing taught me that distance is not the enemy; vagueness is.
The format is the real character here
Fourteen nations played the qualifiers; seven advanced. The eighth entrant is Italy, arriving automatically as reigning champion. Eight nations, one city, a five-to-six-day window, indoor hardcourt. Each tie is two singles and one doubles, best-of-three sets, which means very few matches decide an entire tie, and the quality of a second singles player and a doubles pair matters as much as a headline singles star. Squads therefore outweigh stroke data. That is also why Italy's three consecutive titles read less like a talent story and more like a management story. The wire report names no captains, no coaches and no doubles pairings, so the system claim is inference, not proof.
The Davis Cup sits outside the ATP ranking-points ecosystem. Players come for their country, by national selection, not by obligation. Reuters frames it as the premier men's team competition; that is an institutional frame, not a neutral market description. The centralized Finals model that replaced the old home-and-away format after the 2026 reform is exactly what Bologna extends. So the two questions are simple: who is paying for this model, and what do they get back?
The lesson I learned at Ramna in Dhaka
I learned the economics of the Davis Cup far from any court, inside a sponsorship file at the National Tennis Complex in Ramna, Dhaka, in March 2026. The federation was staging an Asia/Oceania tie, the file had an BDT 800,000 hole, and the room held eleven federation officials, six bank marketing heads and one woman — me. I threw out the standard logo-on-the-net-post deck and built a title package around courtside radio updates, a singles rubber as the hook, and a 2,000-seat gate target. A private bank signed at BDT 1.2 million, and we sold 2,300 tickets across three days. In Dhaka I learned that a title sponsor is not a logo; it is a local myth you sell first. That tie had no sponsor history, so I wrote the category before the contract: banking. Reading the Bologna bracket now, I keep reopening that sheet.
Host-dynasty combination: revenue concentrated in one city
Bologna hosts. Italy defends, chasing a fourth consecutive title. Read together, the economic transmission becomes clear: ticketing, hospitality, hotels, transport, food and beverage, and the host region's broadcast halo all compress into one place, across six days. A fourth title would lift Italian tennis brand equity, and brand equity eventually translates into sponsor pricing and ticket pricing.
A caution belongs here. The host-city model produces revenue that is dense but geographically narrow. It does not distribute evenly across eight participating markets. And the second question is governance, not sport: when the host city also houses the reigning champion, rival federations' boards weigh whether travelling is worth it, because participation is a national selection decision, not a rule. The neutral-venue-versus-home-advantage debate is therefore a commercial risk, not only a fairness footnote. In an event whose product is participation, the price is set by how valuable participation feels.
Category before contract
Using the 2026 method, I drafted the sponsor categories Bologna needs before anyone drafts a rights paper: banking and insurance, telecom and broadband, energy and utilities, streaming platforms, apparel, ticketing and hospitality platforms. Italy's home market is deep in the first two, because domestic institutions can price a domestic dynasty story. But the same bracket creates a second category that did not exist last year: Korean corporate budgets. South Korea has reached the Final 8 for the first time. What matters more than who played where in qualifying is that a telecom or electronics board in Seoul now has a story to buy. The category exists before the paper; the rights deck follows it, never the reverse. In my experience banking, telecom and insurance all sell in exactly that order — myth first, logo second.
Media rights: centralization gains, and what they cost
One venue, one clean international feed, fixed camera positions, a single broadcast window — that is a tidy product. Selling a concentrated knockout week into markets with no participating team is far easier when you do not have to explain eight venue logistics. But tidy is not the same as bigger. The old home-and-away format made each tie its own market, its own title sponsor, its own local radio, its own gate. Centralization closed sixteen local myths and opened one city's larger door.
From two time zones away, I audited thirty-two World Cup sponsor activations in 2026 and watched the same failure repeat: the biggest board buyer was not the most remembered. A snack brand with eleven minutes of mobile-first content outranked a top-tier partner with ninety minutes of perimeter boards. The same arithmetic applies to a five-to-six-day Final 8. Perimeter board time is cheap; mobile-first minutes are scarce. Any federation or event owner selling a signage package without that distinction will wonder why the money underperformed.
The COVID lesson: price the camera, not the seats
When the 2026 shutdown emptied stadiums, I did not mourn the seats; I priced the camera. Sponsor contracts I had helped assemble across three markets were suddenly worth nothing on paper: no crowd, no signage value, no hospitality. In six weeks I rebuilt a valuation model that priced only what survived — broadcast close-ups, virtual board replacement, social clip rights. I took it to two federations and one club. One federation accepted a 40 percent credit against the following season; the other two called it too theoretical. The club that accepted renewed two years later at 15 percent above the original fee.
That sheet is open again for Bologna, because the risk is identified: November 24 to 29 sits immediately after the ATP Finals. Anyone going deep in Turin has a near-zero recovery window before national duty. If names withdraw, what survives here is broadcast close-ups, doubles rubbers, national anthems, Bologna crowd noise, virtual boards and social clip rights. What dies is the gate, hospitality, courtside signage value and sponsor day. I would cut the hospitality-heavy tier entitlements and per-tie title sponsors. I would keep digital boards, clip rights and broadcast integration. In an empty stadium, the product that survives is the real product.
Germany's single point of dependency
The Britain v Germany line carries a structural risk. Germany's recent picture is built around one name. The report calls Zverev a newly crowned US Open champion; I treat that as asserted but unverified. Assume it is true. The question remains: weeks after a Slam, on indoor hardcourt, in a team format, does he arrive as a confidence surge or a let-down? This source offers no data for that judgement. The management decision is still hard, and it involves load and the doubles cushion. There is also commercial transmission: a Slam champion's halo works on his personal endorsement market during the Davis Cup window. Germany's ceiling is pinned to one man's decision that is not yet on paper.
A 32-time champion nation, outside the eight
The United States has won the competition 32 times and holds the deepest history in the event, yet it lost to the Czech Republic in qualifying and is absent from the Final 8. That is an institutional divergence between brand and current results, and it is the most commercially significant fact in the bracket. In the US market, broadcast pricing depends heavily on whether the home team is present. Without it, a network's seven-day studio plan changes, and US sponsor activation budgets shift elsewhere. Legacy is a brand; the Final 8 is a scoreboard. They are separate books. Domestic scrutiny of selection and player availability may take more space in US media than the tournament week itself.
Korea's debut and the map of eight
Seven of the eight Final 8 nations are European; Canada is the only non-European side. The competitive centre of gravity remains European even as Korea arrives. Korea's debut is still a genuine structural milestone, and it can transmit upstream: national-team breakthroughs typically accompany domestic junior enrolment and investment upticks. The report names nobody on Korea's squad, so this is direction, not data. For sponsor storytelling it remains usable: a Korean corporate brand buying in is not buying seats or boards, it is buying a category — first into a new Asian tennis market. The question is whether anyone wrote that story down, how early, and who got there first.
What incentives exist without ranking points
The Davis Cup sits outside the ATP ranking-points ecosystem, so participation rests on goodwill, prestige and selection politics rather than enforcement. That makes competitive integrity dependent on player cooperation. Every federation faces one large management decision: does the top player commit, or take off-season rest? That call is often negotiated and reputation-sensitive. If rest wins, the product thins — and that is a legitimate decision, not a rule violation.
Contrarian angle: the story is not dynasty versus debutant
November coverage will almost certainly run two storylines: Italy's four-peat and Korea's first appearance. Both are true, both are in the facts, both are easy to sell. My objection is not to the prediction; it is to the structure. The centralized Finals model, sold as a commercial modernization, simultaneously shrank the sellable surface. Where the old format gave eight to sixteen nations their own gates, title sponsors, radio and category myths, the current one gives one city's gate, one host's categories, one international feed. The top line tidied up; the floor contracted. Tidy and bigger are not the same thing, and during a sponsor-deck build the difference is decisive. Second uncomfortable point: this event's value is set not by who wins, but by whether eight or ten top names actually walk onto the court. An event whose quality rests on participant goodwill is, stated honestly, a contract with one unsigned party — and a draw announcement is not a signature.
Closing
The watchlist is short and heavy. Will Zverev play, what quality of singles player does Korea bring, and how fast do federations confirm rosters after Turin? Those three determine whose six days in Bologna are worth something. And the line that was missing from the wire altogether is who set the price of the tickets, the feed and the boards — because in an event built on goodwill, the real question always belongs to an accountant, not a fan: who paid the bill, and what came back?